Connecticut Asset Protection Attorneys

Protecting what you have built requires more than reacting after a problem occurs. Effective asset protection planning is generally most useful when it is considered before a lawsuit, creditor claim, long-term-care need or other financial concern becomes immediate.

Drazen Rubin Law helps Connecticut individuals, families and business owners evaluate lawful asset protection strategies in the context of their broader estate, tax, business and long-term-care planning needs.

Depending on the circumstances, planning may involve trusts, business entities, ownership and titling strategies, retirement assets, Medicaid considerations and other legal tools.

No single asset protection strategy is appropriate for everyone. The right approach depends on the assets involved, the risks being considered, the timing of the planning and applicable Connecticut and federal law.

Schedule a Consultation
A couple beside a mature tree and a Connecticut-style home

What Does a Connecticut Asset Protection Attorney Do?

A Connecticut asset protection attorney helps individuals and families evaluate legal strategies that may reduce exposure of certain assets to future creditors, lawsuits, long-term-care costs or other financial risks. Planning may involve trusts, business entities, asset ownership, estate planning and Medicaid considerations, depending on the client’s circumstances and applicable law.

Asset protection planning may involve:

  • Trust and estate-planning strategies
  • Business and ownership structures
  • Long-term-care and Medicaid planning
  • Review of asset titling
  • Retirement and protected-asset considerations
  • Coordination with tax and financial advisers when appropriate

The objective is not to hide assets or avoid lawful obligations. Asset protection planning should be undertaken in compliance with applicable law and with a clear understanding of the legal, tax and financial consequences of any strategy being considered.

When Should You Consider Asset Protection Planning?

Asset protection planning can arise in many different situations. Some clients are concerned about business or professional liability. Others are thinking about long-term care, estate planning or how property is owned.

Speaking with an attorney may be worth considering when circumstances such as these apply.

You Are Concerned About Future Lawsuits

Lawsuits and creditor claims can arise from business activity, real-estate ownership, accidents, contractual disputes and other circumstances.

An attorney can help review how assets are owned, what legal protections may already apply and whether additional planning should be considered.

Asset protection is generally more effective when it occurs before a known claim or creditor issue arises.
You Own a Business or Rental Property

Business ownership and real-estate ownership can create legal and financial exposure.

Depending on the situation, an attorney may discuss business entities, ownership structure, insurance coordination, estate planning and other strategies designed to separate or manage different categories of risk.

The appropriate structure depends on the business, the property, the owners and the specific legal issues involved.

You Are Planning for Long-Term Care

For many families, asset protection becomes a concern when they begin thinking about assisted living, nursing-home care or other long-term-care needs.

Planning may involve evaluating assets, ownership, estate-planning documents, public benefits and Medicaid or Title XIX eligibility.

Because these rules are complex and can change, long-term-care asset planning should be based on current law and the individual’s specific circumstances.

You Are Considering an Irrevocable Trust

Irrevocable trusts may be used for a variety of estate, tax, long-term-care and asset-planning purposes.

However, transferring property to an irrevocable trust can affect control, access to assets, taxes, Medicaid eligibility and other legal rights.

Before creating or funding an irrevocable trust, it is important to understand both the potential benefits and the limitations.

You Want to Review How Assets Are Titled

The way an asset is owned can affect control, transfer at death, creditor exposure, taxation, Medicaid eligibility and estate administration.

Asset protection planning may therefore include reviewing ownership of:

  • Real estate
  • Bank and investment accounts
  • Business interests
  • Retirement accounts
  • Trust assets
  • Jointly owned property

Retitling property can have significant consequences and should not be done solely for asset protection without considering the broader legal and financial impact.

Your Financial or Family Circumstances Have Changed

Major changes can make it appropriate to revisit an existing plan.

These may include:

  • Starting or selling a business
  • Purchasing investment property
  • Marriage or divorce
  • Receiving an inheritance
  • Retirement
  • A diagnosis or change in health
  • Increasing long-term-care concerns
  • Significant changes in assets
  • Changes in family relationships

An existing estate or asset protection plan should evolve as circumstances change.

Asset Protection Strategies in Connecticut

Asset protection is not a single document or transaction.

Depending on the client’s goals and circumstances, an attorney may evaluate several different planning tools.

Irrevocable Trusts

An irrevocable trust may be appropriate in certain estate, tax, Medicaid or long-term-care planning situations.

Unlike a revocable trust, an irrevocable trust generally limits the creator’s ability to modify the trust or regain direct ownership of transferred property.

Those limitations are part of what can make an irrevocable trust useful in some planning situations, but they are also why these trusts require careful consideration.

The terms of the trust, the type of assets involved, the identity of the trustee and beneficiaries, timing and applicable law all matter.

Learn More About Irrevocable Trusts

Ownership and Titling Strategies

How an asset is titled can affect legal rights and potential exposure.

Planning may involve reviewing:

  • Individual ownership
  • Joint ownership
  • Trust ownership
  • Business ownership
  • Beneficiary designations

Changing title may affect estate planning, taxes, probate and Medicaid eligibility. Any change should therefore be considered as part of the overall plan rather than as an isolated asset-protection technique.

LLCs and Business Entities

Limited liability companies and other business entities can provide important legal separation in appropriate situations.

They are commonly considered by:

  • Business owners
  • Real-estate investors
  • Owners of rental properties
  • Families with multiple business interests

An LLC is not a universal shield against liability, and its effectiveness depends on how it is formed, maintained and used.

Business-entity planning should also coordinate with insurance, tax and estate planning.

Retirement Assets

Certain retirement assets may receive protections under federal or state law, depending on the type of account and circumstances.

Asset protection planning may therefore include a review of retirement accounts before considering whether funds should be moved or restructured.

Tax consequences can be significant, so retirement-asset decisions should be coordinated with appropriate tax and financial professionals.

Estate and Trust Planning

Asset protection and estate planning often overlap.

Trusts, beneficiary designations, powers of attorney and ownership arrangements can affect how assets are controlled during life and transferred after death.

A coordinated plan considers both questions:

How should assets be protected and managed during life?

and

How should those assets ultimately pass to beneficiaries?

Medicaid and Long-Term-Care Planning

For older adults and their families, asset protection may also involve preparing for possible long-term-care expenses and understanding Medicaid or Title XIX rules.

Planning in this area is very different from general creditor planning.

Medicaid rules govern eligibility, asset transfers, income and other financial considerations. Strategies that may be appropriate in one context may not be appropriate in another.

Explore Elder Law and Long-Term-Care Planning

Planning for Potential Creditor and Liability Exposure

Asset protection planning generally works best when it is proactive.

Once a lawsuit, creditor claim or other legal obligation already exists, the ability to transfer or restructure assets may be limited by laws governing fraudulent or improper transfers and other creditor protections.

For that reason, asset protection should not be approached as a way to move property beyond the reach of an existing lawful claim.

Instead, planning focuses on evaluating potential future risks and considering lawful structures before those risks become immediate.

Depending on the situation, that may include reviewing:

  • Business entities
  • Property ownership
  • Trust structures
  • Contractual obligations
  • Insurance coverage
  • Retirement assets
  • Estate-planning documents

Legal planning should complement, not replace, appropriate insurance and sound financial practices.

Asset Protection and Long-Term Care Planning

Long-term-care costs are one of the most common reasons families begin thinking seriously about asset protection.

A spouse may need nursing-home care. A parent may be diagnosed with dementia. A family may be trying to understand whether Medicaid could eventually become part of the care plan.

These circumstances require a different type of planning than conventional creditor protection.

Medicaid and Title XIX Planning

Medicaid, also known as Title XIX in Connecticut, may help eligible individuals pay for certain long-term-care services.

Eligibility rules can involve:

  • Assets
  • Income
  • Transfers of property
  • Marital status
  • Ownership of a home
  • Trusts
  • Other financial resources

An elder law or asset protection attorney can explain how the rules apply to an individual situation and discuss planning alternatives that may be available under current law.

No attorney can determine Medicaid eligibility responsibly without reviewing the relevant facts.

Long-Term-Care Costs and Asset Planning

Families may have questions about whether long-term care could affect:

  • A home
  • Savings
  • Investment accounts
  • Retirement funds
  • Business interests
  • Property intended for children or other beneficiaries

The answer depends on the particular asset, how it is owned, who owns it, the timing of planning and the applicable benefit rules.

This is why asset protection and long-term-care planning should be coordinated rather than handled as unrelated issues.

Why Timing Matters

Timing can be particularly important in Medicaid and asset protection planning.

Transfers made for planning purposes may be subject to Medicaid rules and other legal restrictions.

Families should therefore avoid transferring property, adding names to deeds or accounts, or making large gifts solely based on general information found online.

An attorney can help explain the legal and financial consequences before significant changes are made.

Can an Irrevocable Trust Be Part of an Asset Protection Plan?

Yes, an irrevocable trust may be one component of an asset protection plan in appropriate circumstances.

When assets are transferred to a properly structured irrevocable trust, the person creating the trust generally gives up certain rights and control over those assets.

That distinction can be important for estate planning, Medicaid planning, tax planning and potential creditor considerations.

However, an irrevocable trust is not appropriate for every client.

Before creating one, important questions include:

  • Which assets would be transferred?
  • Who will serve as trustee?
  • Who will be the beneficiaries?
  • Will the person creating the trust need access to the property?
  • What are the tax consequences?
  • Could Medicaid rules apply?
  • How might the plan affect the family’s broader estate plan?

Drazen Rubin Law can help clients evaluate whether an irrevocable trust fits within their broader planning objectives.

Read: 3 Reasons to Consider an Irrevocable Trust in Milford

What Is the Difference Between Asset Protection and Estate Planning?

Asset protection and estate planning frequently overlap, but they serve different primary purposes.

Asset protection planning focuses on how assets are owned and structured in light of potential financial risks, including certain creditor claims, lawsuits or long-term-care concerns.

Estate planning focuses on how assets should be managed during incapacity and distributed after death.

Estate planning commonly involves:

  • Wills
  • Trusts
  • Powers of attorney
  • Health care directives
  • Beneficiary planning

Asset protection may involve some of the same tools, but the legal objective is different.

For many individuals and families, the most effective approach is to consider both areas together.

Why Work With Drazen Rubin Law?

Asset protection decisions can affect estate planning, taxes, business ownership, public benefits and long-term-care planning.

For that reason, these issues should not always be evaluated separately.

Integrated Estate and Elder Law Planning

Drazen Rubin Law works with individuals and families on elder law, estate planning, Medicaid planning, long-term care, trusts and related matters.

That broader perspective can be important when an asset protection decision affects multiple areas of a client’s plan.

Tax Planning Experience

Certain asset protection strategies can have tax consequences.

Franklin A. Drazen holds an advanced law degree in taxation, and the firm advises clients on personal and business tax planning in addition to estate and elder law matters.

Where tax issues are relevant, planning can be evaluated within that broader context.

Planning Based on the Individual

An asset protection strategy that makes sense for one person may be inappropriate for another.

Relevant factors can include:

  • Age
  • Health
  • Family structure
  • Type and value of assets
  • Business ownership
  • Real-estate ownership
  • Long-term-care concerns
  • Tax considerations
  • Existing legal obligations
  • Estate-planning objectives

The purpose of legal planning is to understand those circumstances before choosing a strategy.

Asset Protection Planning Throughout Connecticut

Drazen Rubin Law assists individuals and families with asset protection, estate planning, elder law and related matters throughout Connecticut.

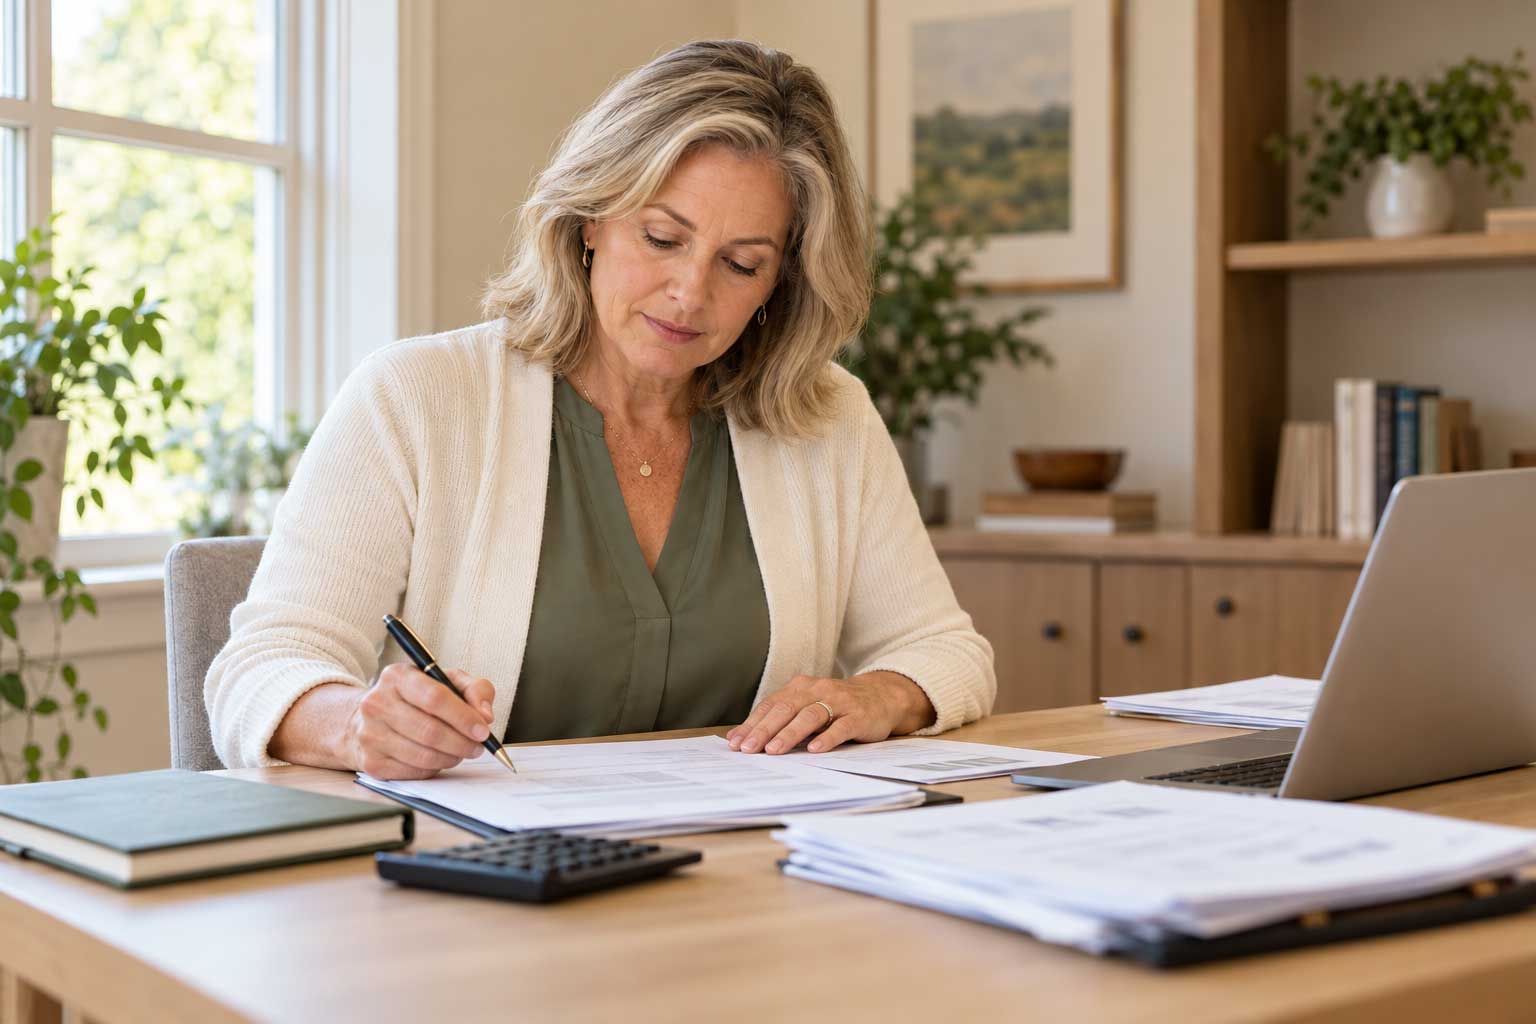
A business owner reviewing financial documents at her desk.

Asset Protection Attorney in Milford, CT

Our principal office is located in Milford.

We assist individuals, families and business owners with asset protection planning involving trusts, estate planning, long-term-care concerns, ownership structure and related legal issues.

Asset Protection Services for New Haven and New Haven County

Clients in New Haven and throughout New Haven County may seek asset protection advice for many reasons, including business ownership, real estate, estate planning and long-term-care concerns.

Drazen Rubin Law can review the circumstances involved and explain planning options that may be appropriate.

Asset Protection Services for Trumbull and Fairfield County

We also assist individuals and families from Trumbull and communities throughout Fairfield County with asset protection and related planning needs.

Planning may involve trusts, estate planning, Medicaid considerations, long-term care or other legal issues depending on the client’s goals.

West Hartford

Drazen Rubin Law also maintains a West Hartford location available by appointment.

Connecticut Asset Protection FAQs

An asset protection attorney evaluates legal strategies that may help reduce the exposure of certain assets to future financial risks. Depending on the circumstances, planning may involve trusts, business entities, asset ownership, estate planning, Medicaid planning and other legal tools.

Asset protection planning is generally best considered before a lawsuit, creditor claim or other legal problem has arisen. Once a known claim exists, laws governing transfers and creditor rights can significantly limit available options.

An irrevocable trust may provide asset protection or other planning benefits in certain circumstances, but the result depends on the terms of the trust, the assets transferred, timing, applicable law and the reason for the planning. Irrevocable trusts also involve important limitations and should not be created without understanding the consequences.

Asset protection can be part of long-term-care and Medicaid planning. The available strategies depend on the individual’s assets, income, family circumstances, timing and applicable Medicaid rules. Planning should be based on current law and the client's specific situation.

Medicaid asset protection planning involves evaluating how assets, income, transfers and other financial circumstances may affect eligibility for Medicaid long-term-care benefits. It may involve trusts or other planning tools, but no single strategy is appropriate for every applicant.

No. Asset protection generally focuses on managing exposure to certain financial risks, while estate planning focuses primarily on incapacity, asset management and transferring property at death. The two areas often overlap.

An LLC can provide legal separation between certain business liabilities and personal assets when it is properly formed and maintained. However, an LLC does not eliminate every type of liability and should be coordinated with insurance, tax and legal planning.

Transfers made after a lawsuit, creditor claim or legal obligation has arisen can be subject to significant legal restrictions. Asset protection should not be used to hide assets or avoid existing lawful obligations. Anyone facing an existing claim should obtain individualized legal advice before transferring or retitling property.

Talk With a Connecticut Asset Protection Attorney

Asset protection planning is most effective when it is based on your actual circumstances rather than a one-size-fits-all strategy.

Whether you are concerned about future liability, business or real-estate ownership, long-term-care costs, Medicaid planning, irrevocable trusts or how asset protection fits within your estate plan, Drazen Rubin Law can help you evaluate the legal issues involved and understand the planning options that may be available.

Contact Drazen Rubin Law to Schedule a Consultation

Milford Office

245 Cherry Street

Milford, CT 06460

Phone: 203.877.7511

West Hartford — By Appointment Only

836 Farmington Avenue, Suite 136

West Hartford, CT 06119

Important Information

The information on this page is provided for general informational purposes and is not legal advice. Asset protection, tax, Medicaid and creditor laws can change, and their application depends on the facts of each matter. Reviewing this website or contacting Drazen Rubin Law does not, by itself, create an attorney-client relationship. Do not transfer, retitle or otherwise dispose of assets based solely on general information found on this website. Consult a qualified attorney regarding your individual circumstances.